Medicare Advantage Plans Suck. You Just Don't Find Out Until You're Sick.
Watch this clip from John Oliver's Last Week Tonight (HBO) on why Medicare Advantage isn't the deal it looks like — fair warning, it's HBO, so the F-word makes an appearance. Then let Ricky show you what actually fits your situation, at no cost to you.
Time-sensitive: If you're new to Medicare Advantage, you have a 12-month window to switch back with guaranteed Medigap coverage. Miss it, and insurers can deny you or charge more for good.
4 Important Things You Need To Know Before You Choose a Medicare Advantage Plan
Medicare Advantage — also called Medicare Part C — is offered by private insurance companies, not the government. Instead of the government paying your doctor directly for whatever care you need, like Original Medicare does, it pays your insurance company a fixed amount per month to manage your care instead. That single structural difference is what shapes everything else: network rules, referrals, and the approvals your care has to go through before it happens.
The insurance company gets paid the same whether you're healthy or not.
That single incentive shapes network limits, referrals, and every approval you'll need.
You don't just pick a doctor — you pick a network.
And that network can change, or drop your doctor, every single year.
"Necessary" isn't decided by you or your doctor.
Prior authorization means your insurance company signs off on your care before it happens.
You're locked in for the full year.
If the plan doesn't work once you're sick, you wait for the next Annual Enrollment Period to leave.
Independent — He Shows You Every Option, Not Just One Plan
Ricky isn't tied to a single insurance company. As a licensed, independent agent, he reviews your actual doctors, prescriptions, and health needs against every option available to you — Medicare Advantage, Original Medicare, and Supplement plans alike. There's no cost to talk it through and no pressure to enroll in anything. If an Advantage plan really is the right fit for you, he'll tell you that too.
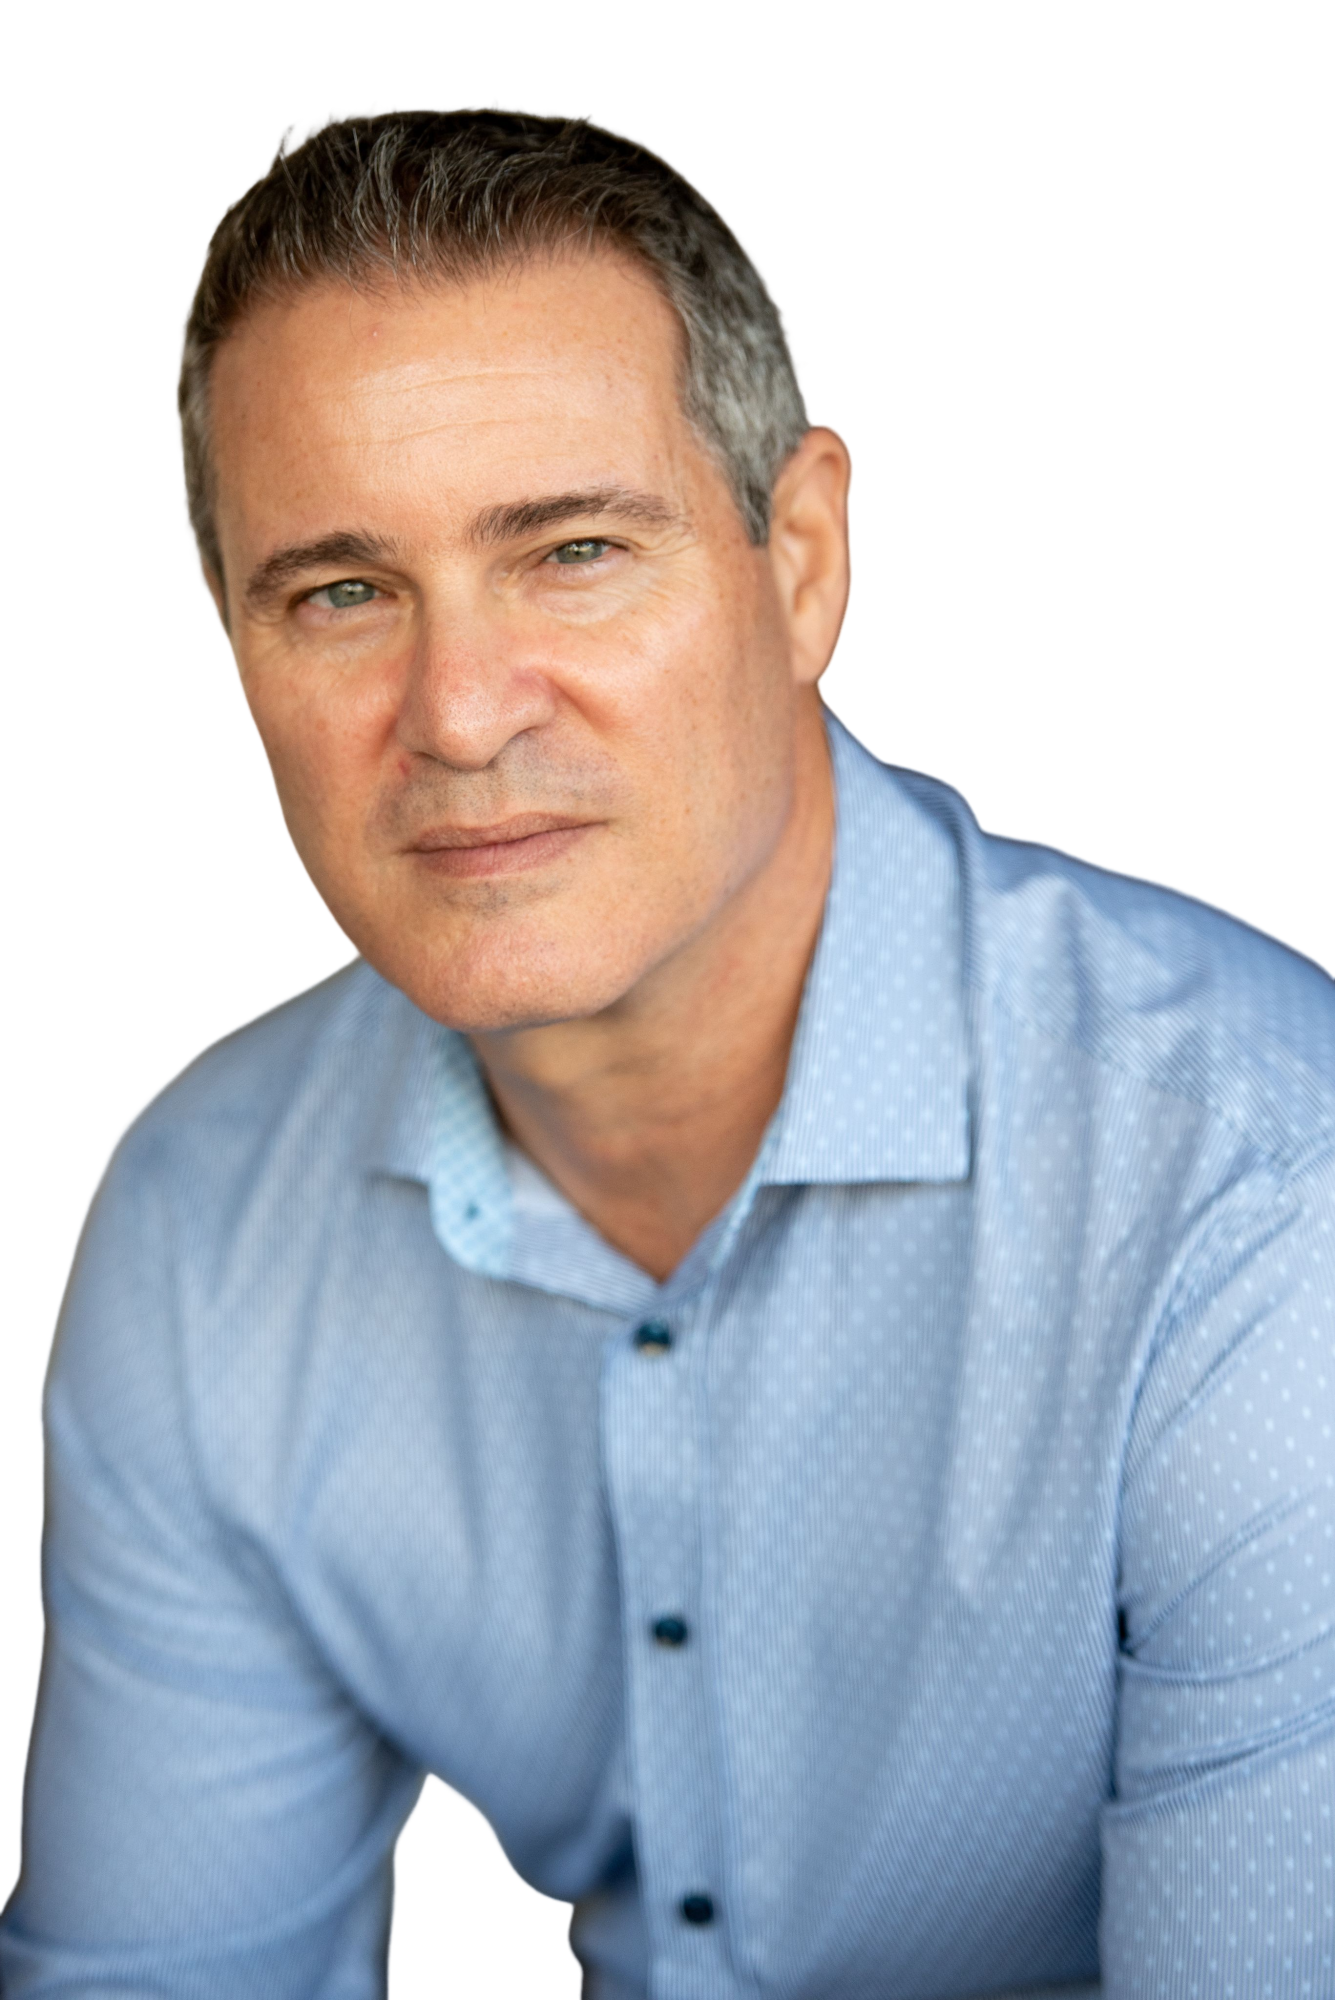
Ricky Rash
After serving in the real estate & mortgage industry for 20 years, I made the transition to Life & Health Insurance, with an emphasis on Medicare & Retirement. Since obtaining my license in 2009 and launching my agency with Miguel Moita in 2012, we have helped thousands of people with their financial planning and insurance needs, including Medicare Advantage & Supplemental Plans, Long Term Care, Life Insurance, Final Expense, Annuities, Major Medical Insurance & Disability Insurance.
Frequently Asked Questions
What's the actual difference between Medicare Advantage and Original Medicare?
Original Medicare (Parts A & B) is run directly by the federal government. You can see any doctor or hospital nationwide that accepts Medicare, with no referrals and no prior authorization required for most care. Medicare Advantage (Part C) is run by private insurance companies instead — the government pays your insurer a fixed monthly amount to manage your care, rather than paying your doctor directly. That's what allows the plan to require a network, referrals, and prior authorization before certain care happens — restrictions Original Medicare simply doesn't have.
Why do Advantage plans cost $0 a month?
Advantage plans can offer a $0 premium because the government is already paying the insurance company a set amount per member every month. The insurer isn't charging you on top of that — it's building its profit into how it manages your care instead. That's also why plans include extras like gym memberships or dental coverage: they're funded by that same fixed payment, and they're a big part of how these plans get marketed.
What is prior authorization, and why does it matter?
Prior authorization means your insurance company has to approve certain care — a procedure, a specialist visit, a piece of equipment — before you're allowed to have it. Your doctor can recommend something, but the plan can still say no, or make you wait. Delays and denials both happen, and they can happen at the exact moment you need care fastest.
Can I switch back to Original Medicare later?
Yes, but it's not always simple. You can switch during the Annual Enrollment Period every fall, but if you want to add a Medicare Supplement at that point, the insurance company can medically underwrite you — meaning they can charge you more, or in some cases deny coverage, based on your health. There's a one-time window right when you first join Medicare where that underwriting doesn't apply. After that, switching back isn't guaranteed to look the way it did the first time.
What is the Annual Enrollment Period?
It's the one window most people get each year — October 15 through December 7 — to change Medicare plans. Miss it, and in most cases you're locked into your current plan for another full year, even if it stops working for you.
Will my doctor still take my plan?
With Original Medicare, almost certainly yes — most doctors nationwide accept it. With Medicare Advantage, it depends on whether your doctor is in that specific plan's network, and networks can change year to year. A doctor who's in-network this year isn't guaranteed to be in-network next year.
What happens if I get seriously ill on an Advantage plan?
This is when the plan's rules matter most — network limits, referrals, and prior authorization all apply to serious and complex care too, not just routine visits. You can still owe up to the plan's yearly out-of-pocket maximum, which can run into the thousands, and getting specialists or treatment approved can take time you may not have.
Does it cost anything to talk to Ricky?
No. It's a free, no-obligation conversation — he'll go over your specific situation and give you a straight answer, whether or not you end up working with him.
Find Out What Your Coverage Is Actually Costing You.
Schedule a free, no-obligation Medicare review. We'll go over your current coverage, walk you through your options in plain English, and give you a straight answer about what's actually right for you.
1 786-791-5440 · ricky@RickyRash.com · RickyRash.com